
GSTR-2B is the auto-drafted inward statement: the portal composes it every month from what your suppliers filed, and it determines how much input tax credit is available to you. In xMatix the statement holds two sides in the same tables: a books side materialized from the purchase tax you posted, and a portal side holding the statement as the portal drafted it. Keeping both lets you reconcile them section by section before the figures flow into GSTR-3B.
The statement's sections
| Section | What it is | Books side? |
|---|---|---|
| B2B | Inward supplies from registered suppliers | Yes — built from your posted bills |
| CDNR | Supplier credit / debit notes | Yes — built from your posted purchase returns |
| B2BA / CDNRA | Amendments to the above | Portal side only |
| ISD / ISDA | Input Service Distributor credits | Portal side only |
| IMPG / IMPGSEZ | Import of goods — overseas and from SEZ | Portal side only |
| ECO / ECOA | Supplies through e-commerce operators | Portal side only |
| ITC summary | The portal's own ITC available / not-available rollup | Portal side only |
Only what your purchase ledger can know is derived from it; everything else — amendments, ISD credits, imports — lives on the portal side of the statement's records.
Prerequisites
- The period's bills and purchase returns approved and posted, with supplier accounts carrying their GSTINs.
- The GSTIN's statement record for the period, provisioned via the GST console.
Procedure
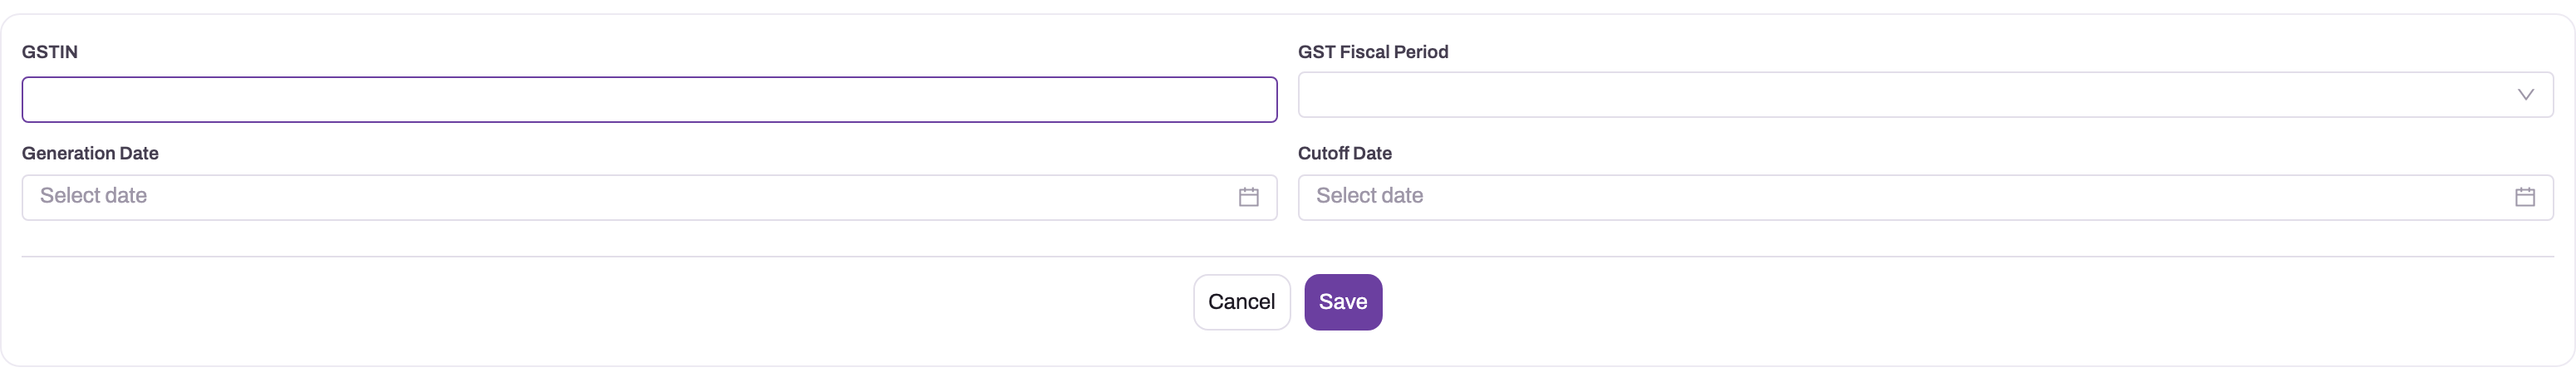
- 1
GSTIN identifies the registration whose eligible inward supplies are being reviewed.
- 2
GST Fiscal Period bounds the books and portal records included in this statement.
- 3
Generation Date records when the portal statement became available.
- 4
Cutoff Date explains which supplier filings were visible in this static statement.
- 5
Save creates the header; processing and reconciliation remain explicit later actions.
Step 1 — Process the books side
Open or create the statement and verify its GSTIN, fiscal period, generation date and portal cutoff before running Process GSTR-2B Data. The processor reads input-tax lines for exactly that recipient GSTIN and period, builds B2B from posted bills and CDNR from purchase returns, and retains exempt lines. Wait for the run summary, then reconcile its processed/skipped/failed counts to the source-document population before importing portal data.
Processing is incremental—unchanged data is skipped and changes merge into existing rows. Existing IMS status values on rows can survive that merge. Verify the last-processed marker advances. Use rebuild only for an approved repair because it replaces the books-side rows, including any IMS state held on those rows.
Step 2 — Bring in the portal statement
Download the portal statement for the same GSTIN, period, generation date and cutoff, retain the source file, and import it into the portal-side section records using data import. Review import validation and row counts before accepting the load. Portal-only sections—imports, ISD, amendments and e-commerce—prove completeness, so an apparently clean books side is not enough when those sections are absent.
Step 3 — Review the summary
Review every section block on each side: document count, taxable value and tax heads, plus the portal ITC available/not-available rollup. Drill material totals to supplier and document rows and tie the books totals to the purchase-tax controls. Confirm the side selector before recording evidence; books and portal are alternatives for comparison, never figures to add together.
Step 4 — Reconcile the two sides
Open reconciliation only after both sides pass their control totals. It flattens sections and pairs them on statutory natural keys—supplier GSTIN, invoice number and date for B2B; note number/type for CDNR; bill-of-entry number/date for imports. Verify the compared GSTIN and period in the header, then work every non-matched row:
| Status | Meaning |
|---|---|
| Matched | Both sides agree on every tax head and the value |
| Mismatch | Both sides have the document; amounts differ |
| Missing in GSTN | In your books, not in the portal statement — the supplier has not reported it |
| Missing in books | The portal has it, your books do not — a bill you have not recorded |
A supplier-reported invoice missing from your books usually means an unposted or mis-dated bill; a books document missing from the portal means chasing the supplier — their filing, not yours, is what makes the credit available.
Step 5 — Interpret imported IMS status correctly
Some GSTR-2B section rows carry an ImsStatus value such as A (accepted) or R (rejected). GSTR-3B Compute excludes rows whose stored IMS status is R from box 4A. However, the current GSTR-2B server handler exposes only Get, Process and Reconciliation actions: it has no supported Accept, Reject, reason or reviewer action. The reconciliation grid must therefore be used to investigate differences, not presented as a persisted decision-approval workflow.
If an integration or controlled data load supplies IMS status, verify the value against its external evidence before Compute. Do not rely on the legacy grid's visible Accept/Reject labels as proof of a saved decision; that client currently changes only local screen state and does not write an audited action to the server.
Expected result
Books and portal sides belong to the same GSTIN, period and cutoff, reconcile to their source control totals, and classify every difference. Where an authoritative import has supplied IMS status, GSTR-3B excludes rows stored with status R. The GSTR-2B workflow itself does not currently capture the decision, reason or reviewer.
Two protections worth knowing
- The statement cannot be deleted. It is a statutory auto-drafted statement; deletion is blocked.
- Re-processing never touches the portal side. The books materialization is scoped to its own side, so loading the portal statement and re-processing your books are independent, repeatable steps.
The books processing can also run unattended on a schedule (finance.gstr2b.process), with the same skip-unchanged incremental behavior as an on-demand processing run.
Common problems
A bill is missing from the books side. Check that it is posted, dated inside the period, recorded against a supplier account, and under the right recipient GSTIN. Purchase returns appear in CDNR, not B2B.
A section is empty on the books side. If it is one of the portal-only sections (imports, ISD, amendments, e-commerce), that is by design — your ledger cannot derive it; load the portal statement.
Accept or Reject is missing, or does not persist. That is a current product limitation, not a permission issue: the GSTR-2B server handler has no Accept/Reject action and no reason/reviewer audit contract. Use imported authoritative IMS status only where your configured integration or data-control process supplies it.
Related topics
- Input tax credit management — what happens to the credit after the statement.
- GSTR-3B — the summary return — where the statement's ITC lands.
- AR and AP subledgers — the purchase documents behind the books side.