
GSTR-1 is the detailed outward-supplies return: it reports sales at the document level, table by table. xMatix never asks you to key invoices into it — every posted sales invoice, credit note and debit note has already captured its tax lines, and the return is materialized from those lines. Your work is to process, review, reconcile and file.
Prerequisites
- The period's sales documents approved and posted — an unposted invoice has no tax lines and cannot appear in the return.
- The GSTIN's return record for the period, provisioned via the GST console.
- Permission to run the GSTR-1 actions.
Procedure
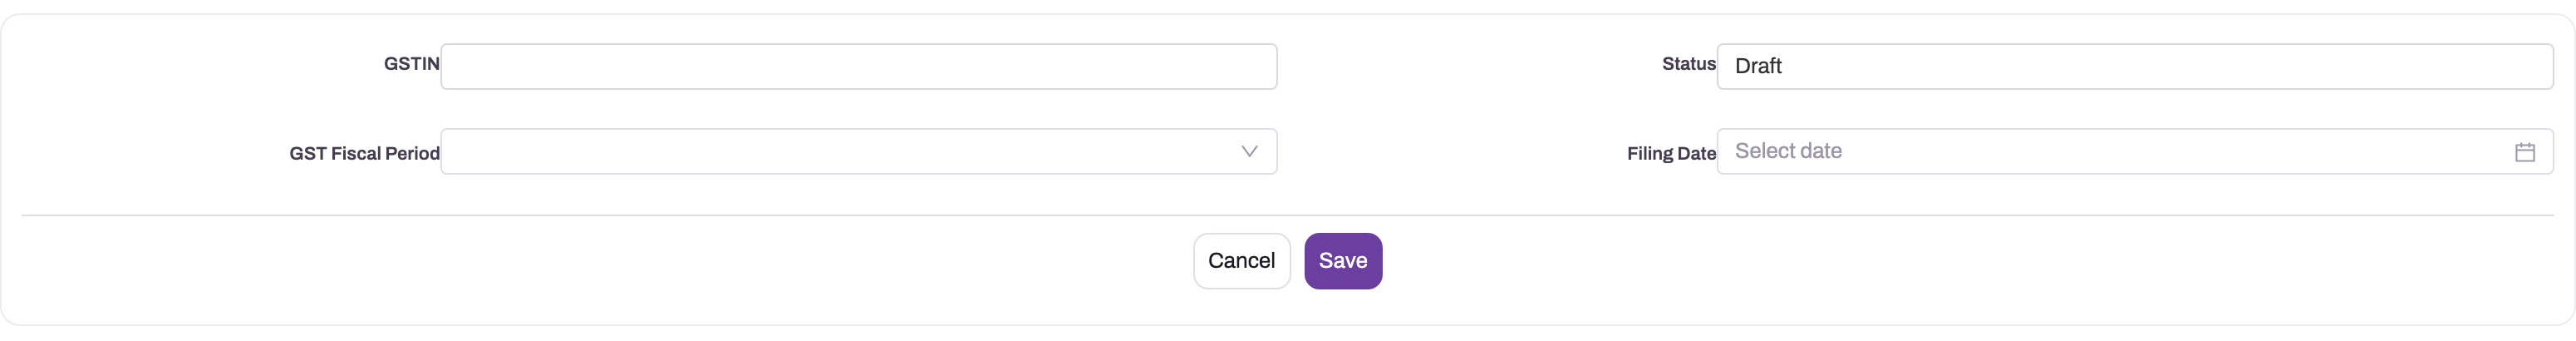
- 1
GSTIN chooses the registration whose outward supplies are processed.
- 2
Status remains Draft while processing and reconciliation are still allowed.
- 3
GST Fiscal Period bounds the source documents included in the return.
- 4
Filing Date is recorded only after filing and turns the return into a statutory snapshot.
- 5
Save creates the return shell; processing populates its statutory tables afterwards.
Step 1 — Process the return
Open the return from the GST console and verify its GSTIN, fiscal period and Draft status before running Process GSTR-1 Data. Record the source-document cut-off and wait for the processing summary; do not navigate away while the first materialization is running. The processor reads output-tax lines for exactly that GSTIN and period and routes each document into its statutory table:
| Return table | Filled from |
|---|---|
| B2B (incl. SEZ, deemed export) | Invoices to registered buyers, one row per invoice with per-rate tax detail |
| B2C Large | Inter-state B2C invoices over the per-invoice threshold in force for the period |
| B2C Small | All other B2C supplies, aggregated by place of supply and rate |
| Exports | Export invoices, split by with/without payment of tax |
| Credit / debit notes | Posted sales credit and debit notes — credit notes net the liability down |
| Nil-rated / exempt | Supplies with taxable value and no tax, aggregated (you can re-split the figure across the statutory columns; your split is preserved) |
| HSN summary | Every supply grouped by HSN/SAC and rate, credit notes netted |
| Documents issued | Not derived — maintain this table yourself; it needs your document series, which tax lines do not carry |
Processing is incremental: unchanged data is skipped, while changes merge into existing rows so prior row decisions survive. After each run, reconcile processed/skipped/failed counts and confirm the data watermark or last-processed time advanced. Use Rebuild only for an approved repair because it deliberately discards prior reconciliation decisions.
Step 2 — Review the summary
Review every statutory summary block—document count, taxable value and IGST/CGST/SGST/cess—and drill into material or unusual totals to their source documents. Tie the net outward liability to the sales/tax control reports for the same GSTIN and period. The grand total correctly excludes HSN summary and documents-issued tables to avoid double-counting, and credit notes are netted; account for those rules explicitly in the reconciliation rather than adding all displayed blocks together.
Step 3 — Reconcile books against the portal
Import or refresh the portal side, then open Reconciliation. Confirm the portal period and GSTIN match the books snapshot before interpreting results. The view pairs rows on statutory natural keys—buyer GSTIN plus invoice number for B2B, note number/type for notes and equivalent keys elsewhere—and assigns a status:
| Status | Meaning |
|---|---|
| Matched | Both sides agree within a one-rupee tolerance |
| Mismatch | Both sides have the document; amounts differ |
| Missing in GSTN | Your books have it; the portal side does not |
| Missing in books | The portal side has it; your books do not |
Step 4 — Record decisions on the differences
Open every Mismatch or Missing row to its source evidence before choosing an action. Two actions resolve filing differences without touching the ledger:
- Carry forward reports the selected documents in the next period's filing instead of this one — the usual answer for a document the portal never received before you filed. The next period picks it up automatically, even if its return has not been provisioned yet.
- Ignore drops the documents from this filing outright.
Verify the row's decision tag plus the ignored/carried-out/carried-in summary counts. The current Carry Forward and Ignore actions persist the selected row flags, but they do not collect a reason, reviewer or approval audit field; retain that evidence in your approved workpaper if your control process requires it. Aggregated rows such as B2C Small and HSN have no document identity and cannot take a row decision. If carry-forward is refused because the next period is already filed, stop and process the statutory amendment rather than forcing the document out of both periods.
Step 5 — File and record the filing
After an authorized reviewer approves the final totals and exception register, file on the GST portal. Then run the GSTR-1 filing-record action with the filing date and verify that IsFiled is set, Status becomes Filed, and processing is disabled. This action records the state in xMatix; the GSTR-1 header has no acknowledgment, ARN or portal-reference field and the action does not retain one. Keep the portal acknowledgment in your controlled filing evidence. A filed GSTR-1 is a statutory snapshot: later ledger changes cannot regenerate it, and corrections use an amendment in a later period rather than reopening this return.
Expected result
The return contains the correct GSTIN and fiscal-period outward supplies, reconciles books to portal with every difference either resolved or explicitly decided, and ties to the approved tax controls. Recording the filing date freezes the xMatix snapshot and prevents accidental reprocessing; portal acknowledgment evidence must be retained outside the GSTR-1 header.
Keeping it fresh automatically
The same processing can run unattended: schedule the GSTR-1 processing job (finance.gstr1.process) on a recurrence from the Schedules screen. In discovery mode it processes every unfiled return whose period is open, across all filer GSTINs; it skips unchanged periods, preserves reconciliation decisions, and skips filed returns rather than failing on them. The run summary reports processed, skipped and failed counts on the Jobs screen.
Common problems
An invoice is missing from the return. Work through the source document: is it posted (drafts capture nothing)? Is its document date inside the period? Was it issued under the same GSTIN the return is for? Was it ignored or carried forward in a reconciliation decision — the summary's excluded-document counts will say.
Processing is refused. The return is filed. That is the guard working; raise the correction as an amendment in the next open period.
Related topics
- The GST console
- GSTR-3B — the summary return — Compute prefers a filed same-period GSTR-1 but can fall back to a Draft one.
- Troubleshooting the Tax Center